Abstract
Background/Objective. Kazakhstani women hold tertiary qualifications far more often than men, and account ownership is near-universal for both. This study asks whether that educational advantage appears in two financial outcomes — the capacity to raise emergency funds and formal savings behaviour — among working-age adults.
Methods. Microdata from the World Bank Global Findex 2025 for Kazakhstan. After excluding don’t-know and refused answers and restricting to ages 18–55, 718 cases remain for vulnerability and 726 for savings. The design is cross-sectional and associative. Estimates use the Findex person weight with Taylor-linearized variance and pseudo-maximum-likelihood logistic regression. Because the public release omits cluster identifiers, every test is re-evaluated across intraclass correlations up to .06.
Results. Women hold tertiary education 13.34 pp more often than men (95% CI [6.36, 20.33], p < .001). That advantage does not appear in either outcome. Women save formally less often, and the gap survives adjustment and plausible clustering (OR = 0.618, 95% CI [0.425, 0.899], p = .012). The gender gap in emergency-fund capacity is not significant (+4.16 pp, 95% CI [−0.44, 8.75]). Household income dominates vulnerability (top two versus bottom two quintiles, penalized OR = 0.214, p < .001) and transmits about a fifth of education’s total effect on it. Of two pre-specified interaction hypotheses, one was not supported and one held only on the primary outcome.
Conclusions. In a near-universally banked population, financial vulnerability is stratified by income, and women’s educational advantage does not convert into a savings advantage.
Keywords: financial resilience, gender gap, formal savings, survey-weighted estimation, Kazakhstan, Global Findex.
Introduction
Background and Context
Owning a bank account and being able to withstand a financial shock are different things. Account ownership measures access; the capacity to raise money in an emergency measures resilience. Global financial inclusion policy has spent two decades closing the first gap, and in much of the world it has succeeded. Whether that success carries over to the second is a separate question, and the answer appears to depend on where it is asked.
The distinction between access and engagement runs through this literature. Individual microdata from 37 African countries show that being male, richer, older and better educated all raise the probability of holding an account, with income and education the strongest predictors, and that mobile banking is driven by the same determinants as conventional banking.1 Across 123 economies, account ownership rises with lower account costs, closer branches and stronger legal institutions.2 Financial infrastructure and literacy substitute for one another on the access margin but complement one another on the usage margin, so literacy’s role depends on which margin is measured.3 The first two describe who gets in; none describes what happens to resilience afterwards.
Evidence on what happens afterwards is more divided than summaries of it suggest. Long-run consumption gains and movement out of poverty in Kenya have been attributed to mobile money access, with effects concentrated among female-headed households.4 In Tanzania, mobile money users avoid consumption drops after village-level rainfall shocks, but non-users in the same village gain nothing.5 Using two Ghanaian household surveys and propensity-score methods, financial inclusion has been shown to raise household resilience, though the effect does not vary significantly by gender, and formal savings rather than mobile money drives the gain.6 Pooling eight low- and middle-income countries reveals no independent gender association in mature mobile-money markets but widening gaps in emerging ones.7 Mobile-money use stratifies by age and wealth independently of network access.8 Whether digital finance narrows or widens gender differences appears to depend on the market it enters.
A parallel literature asks whether education closes gender gaps in financial outcomes, and reaches conclusions that disagree by an order of magnitude. Human capital variables including education explain essentially none of the Australian gap, with labour-market variables accounting for roughly a sixth.9 A pooled Latin American analysis attributes 44% of the gap to differences in characteristics — and finds no significant gap at all in Chile.10 A counterintuitive gradient across a dozen countries shows the gap largest in the most developed economies,11 and the Chinese gap has been attributed entirely to differences in how men and women acquire financial knowledge rather than to differences in endowments.12 The Swedish gender gap in stock market participation shrinks substantially once financial literacy is controlled, implicating knowledge rather than preferences.13 Knowledge gaps for women and less-educated adults appear in developed as well as developing markets.14 What replicates is the weak claim that education does not close the gap; the strong claim that education is irrelevant does not.
Problem Statement and Rationale
These literatures have developed largely in parallel, and both are dominated by settings where access itself is still the binding constraint. That leaves a specific question unanswered. In a country where account ownership is already near-universal for both men and women, does a gender difference in financial resilience persist, and does women’s educational advantage appear in financial outcomes at all?
Kazakhstan is a useful place to ask. Account ownership approaches saturation, driven substantially by the digitalisation of pension and social transfer payments rather than by commercial uptake, so access is not the margin on which men and women differ. Women complete tertiary education at higher rates than men. The banking sector is concentrated, and evidence from transition economies suggests concentration and ownership structure shape who gets served in ways aggregate credit growth does not capture. Using more than 16,500 households across 19 Central and Eastern European economies, a higher foreign-bank market share has been shown to widen the credit-use gap between households with and without formal employment,15 while microfinance branch openings in South-East Europe raise the banked share most among low-income, older and transfer-dependent households.16 Bank presence has opposite distributional consequences depending on lender type, which cautions against reading Kazakhstan’s concentrated sector in either direction without individual-level data — including the aggregate-statistics account offered by Bekturganova and Kurmasheva17.
That individual-level evidence is what is missing. A search for peer-reviewed primary research using Findex or Life in Transition microdata to analyse financial inclusion in Kazakhstan at the individual level with design-based estimation returned nothing. What exists falls into three groups: working papers from international financial institutions, which are the strongest regional analyses but are organisational reports; national-journal studies using aggregate banking statistics or localised surveys on rural saving behaviour;18 and multi-country studies in which Kazakhstan is one unreported row. Regional household-level work exists for neighbouring economies: remittance-receiving households in Uzbekistan invest in family enterprise only when remittances are supplemented by other income or savings, so financial constraints bind hardest in rural areas,19 but this work does not address the gender and resilience questions posed here. This search ran through English-language indexes, which cover Russian- and Kazakh-language journals unevenly, so relevant regional work may exist that it did not reach.
Theoretical Framework
This study treats financial inclusion and financial resilience as distinct constructs linked by an incomplete pathway. Inclusion is an access condition: holding an account creates the possibility of saving formally, receiving payments digitally and borrowing on recorded terms. Resilience is a capacity outcome: having something to draw on when an expense arrives. Access enables engagement, engagement may build a buffer, and a buffer produces resilience. Each link can fail independently, so a population can be almost fully included and still substantially unresilient. That the first link can hold while later ones fail is visible in evidence from Nepal, where free savings accounts were opened and used at high rates yet the resulting changes in household outcomes were narrower than the take-up alone would suggest.20
Education is expected to operate through this chain rather than around it. Higher attainment is associated with higher earnings, and earnings permit accumulation. If education raises resilience, income should carry much of that effect, which makes income a mediator on the path from education to resilience rather than a competing explanation. Distinguishing the total effect of education from its income-adjusted direct effect is therefore necessary: conditioning on income and observing attenuation indicates transmission through income, not that education is inconsequential.
Age enters as a possible moderator on two grounds. Lifecycle position determines what a person has had time to accumulate and what obligations they carry. Cohort exposure differs as well: adults now aged 36–55 reached adulthood before or during the collapse of the Soviet savings system, an experience with no counterpart for those now aged 18–35, and one plausibly connected to institutional trust. Trust is a demand-side constraint distinct from access, and its relationship to inclusion is not straightforward: trust in banks has been found lowest in the developed economies that also record the highest levels of financial inclusion,21 while higher trust is associated with greater inclusion at the individual level across 28 countries.22 Neither pattern can be examined here, since the Findex individual file does not record trust.
Objectives and Hypotheses
This study describes how financial vulnerability and formal savings are distributed by gender, age and income among working-age adults in Kazakhstan, and tests three hypotheses stated in the submitted version of this manuscript. Each concerns a specific parameter, and each is a claim about statistical detectability at the available sample size rather than about the magnitude of a population difference. Percentage points are abbreviated pp throughout.
H1. The gender difference in financial vulnerability differs between adults aged 18–35 and adults aged 36–55, tested as an interaction coefficient between gender and age group rather than as a comparison of two subgroup tests.
H2. A gender difference exists in formal savings, tested as a between-gender contrast pooled across ages, with cohort-specific estimates reported descriptively.
H3. Among women, the association between holding a digitally enabled account and financial vulnerability differs between the two age groups, tested as an interaction coefficient.
The three are not equally supported by the literature preceding them. H2 rests on a broad base of cross-country evidence on women’s lower formal savings. H1 extends findings on gender gaps in resilience to a moderation claim that few studies have tested directly.23 H3 rests on the thinnest foundation: the evidence that digital finance has heterogeneous effects across demographic groups is real but contested, as evidence from Cameroon and from Niger illustrates from different angles,24,25 and no prior study has examined age moderation of this association among women in a high-access setting.
One property of the design should be stated at the outset. The analytic sample contains 63 financial-vulnerability events. An interaction test on a binary outcome needs roughly four times the sample of a main-effect test to detect an effect of the same magnitude, so the study is underpowered for the inferential questions posed by H1 and H3. This was a property of the available sample when the hypotheses were written, not a discovery made after the results were obtained.
Significance, Scope and Methodology Overview
The contribution is threefold. Substantively, the study provides an individual-level, design-based account of gender differences in financial resilience in Kazakhstan, in a setting whose near-universal access separates the access question from the resilience question. Methodologically, it demonstrates that the choice between weighted and unweighted estimation changes which results survive, in both directions. Epistemically, it reports one pre-specified hypothesis as tested and unsupported and a second as supported only on the primary outcome.
The analysis covers adults aged 18 to 55, which is 72% of the released Kazakhstan file; results describe working-age adults rather than the Kazakhstani adult population. The design is cross-sectional, so no result supports a causal claim. Wealth stocks, household composition, financial literacy, institutional trust and individual rather than household earnings are not recorded in the Findex individual file, so mechanisms proposed in prior work cannot be adjudicated here. All estimates use the Findex person weight with Taylor-linearized variance; hypotheses are tested by survey-weighted logistic regression carrying interaction terms, with penalized estimation where event counts are low.
Methodology
Research Design and Sample
This is a cross-sectional, observational study of individual-level survey data collected at a single point in time. No treatment was assigned, so the analysis identifies associations rather than causal effects. The design is confirmatory for H1 through H3 and exploratory beyond them; the urban–rural stratification reported in the Results was not pre-specified and is labelled accordingly.
Data come from the World Bank Global Findex Database 2025, Kazakhstan country file26. Findex is administered by Gallup as part of the Gallup World Poll and covers the resident population aged 15 and above through face-to-face interviewing using multistage area probability sampling. The Kazakhstan file contains 1,000 respondents. Seventy were excluded for answering don’t know (n = 50) or refusing (n = 20) on the emergency-funds item, leaving 930 with a valid outcome; restricting to ages 18–55 removed a further 212, leaving 718.
The two age groups are 18–35 and 36–55. The boundary is placed where education completion, household formation and early career give way to peak earning and accumulation, and it separates cohorts by exposure to the post-Soviet transition. It is defensible on these grounds but not uniquely correct. Item-level missingness within the age window was 45 cases on vulnerability, 37 on formal savings and 4 on education; digital account ownership, income quintile, employment and urbanicity were complete.
Variables and Measurements
Financial vulnerability, the primary outcome, is derived from fin24, “Main source of emergency money in 30 days.” Response options 1 through 6 name substantive sources; option 7 records that the respondent could not come up with the money; options 8 and 9 record don’t know and refusal. Vulnerability is coded 1 for option 7 and 0 for options 1 through 6, with options 8 and 9 excluded rather than folded into the zero category. Table 1 gives the full value-label table and the case flow.
The related item fin24a records difficulty of raising emergency funds on an ordered scale, but the codebook restricts it to respondents who reported a main source, so respondents coded 7 on fin24 are routed around it. This was verified against the Kazakhstan file: all 103 respondents with fin24 = 7 have fin24a missing, and all 827 with fin24 between 1 and 6 have it observed, with no exceptions in either direction. Because fin24a has no observed values on the subpopulation of interest, it cannot serve as the basis for an inability indicator. A composite specification combining both items is reported as a robustness check.
Formal savings, the secondary outcome, is derived from fin17a, “Saved at a bank or similar financial institution,” coded 1 for yes and 0 for no, with don’t know and refusal excluded. It measures accumulation over the preceding year, whereas the primary outcome measures capacity at a moment.
Digital financial inclusion is measured by dig_account, defined as holding a mobile money account or an account at a financial institution from which the respondent makes digital payments by card or phone. The variable combines access with a minimal usage threshold rather than capturing access alone. In a market where 86% of respondents hold such an account its discriminating power is limited and the comparison group is small and likely selected, so it is treated as a marker of broader socioeconomic integration rather than an isolable exposure. Covariates are gender, age group, tertiary education, within-economy household income quintile, employment status and urbanicity.
Data Analysis
Weighted proportions are ratio estimators with variance estimated by first-order Taylor linearization, 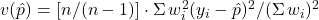 . Confidence intervals for single proportions use the logit transformation; intervals for differences use the normal approximation on the difference scale. Effect sizes for proportion contrasts are Cohen’s h. All tests are two-tailed at α = .05.
Hypotheses are tested using pseudo-maximum-likelihood logistic regression with probability weights normalized to sum to the unweighted sample size. Because the score contribution of observation i is wᵢsᵢ, the robust variance requires a meat matrix of Σ wᵢ²eᵢ²xᵢxᵢ′; this is obtained through the variance-weight argument with an HC0 covariance and an explicit √(n / (n − 1)) correction, a combination that reproduces the standard survey-weighted logistic estimator to a maximum relative difference of 3.6 × 10⁻¹⁶. Only Wald tests are reported, since deviance, AIC and likelihood-ratio statistics are not valid likelihood quantities under pseudo-likelihood estimation.
With 63 vulnerability events against eleven parameters, the full specification yields 5.73 events per variable, below the conventional minimum of ten. Vulnerability models are therefore also reported in a reduced specification collapsing income to three categories and omitting urbanicity, and with Firth penalized estimation, which corrects the small-sample bias that inflates maximum-likelihood coefficients in sparse data; the penalized fits use the same linearized (sandwich) variance as the unpenalized ones. Events per variable for each outcome are given in Supplementary Table R1, and the income coefficient across estimators in Supplementary Table R2. The savings models, with 239 events against ten parameters, carry 23.9 events per variable and are not affected. No correction for multiple comparisons is applied to the primary tests, following Rothman27; Holm-adjusted values are reported alongside.
Because the public release omits cluster identifiers, the linearized variance captures the unequal-weighting component of the design effect and excludes between-cluster variation. The Kish design effect for the analytic sample is 1.236, and the weight distribution is moderately dispersed (coefficient of variation 0.486) with no extreme values (Supplementary Tables R6 and R8); the released weights are already capped at the first and ninety-ninth percentiles, and trimming at the fifth and ninety-fifth percentiles changes no conclusion. Every key test is re-evaluated across intraclass correlations up to .06 assuming an average cluster size of ten. Analyses were conducted in Python 3.13 using pandas, statsmodels, scipy and patsy. A single replication script regenerating every table in the manuscript and in the supplementary document, together with the derived dataset, accompanies this submission.
Ethical Considerations
This study analyses de-identified secondary data made publicly available by the World Bank. No new data were collected and no individual is identifiable in the released file. Informed consent was obtained by Gallup at the point of interview under its own protocols; the present analysis involves no interaction with participants and no identifiable private information.
Results
Results are presented in two parts: the three hypotheses as stated in the submitted manuscript, then analyses that were not pre-specified. All percentages are survey-weighted; all cell counts are unweighted.
| fin24 code | Codebook label | n | Recoded as |
| 1–6 | Named a substantive source of emergency funds | 827 | 0 — not vulnerable |
| 7 | Could not come up with the money | 103 | 1 — vulnerable |
| 8 | Don’t know | 50 | Excluded |
| 9 | Refused | 20 | Excluded |
Note. Case flow: 1,000 raw responses; 930 with a valid outcome after excluding codes 8 and 9; 718 after restricting to ages 18–55. Code 7 is a substantive response option, not a residual category.
| Characteristic | 18–35 women | 18–35 men | 36–55 women | 36–55 men |
| Tertiary education | 35.76% (92/192) | 24.06% (48/146) | 40.39% (129/244) | 29.38% (68/177) |
| Digitally enabled account | 86.19% (171/194) | 85.54% (128/146) | 86.27% (214/245) | 88.30% (158/178) |
| Saved at a financial institution | 23.18% (49/184) | 28.35% (43/142) | 30.88% (79/233) | 41.99% (70/167) |
| Financially vulnerable | 13.49% (25/184) | 6.51% (8/141) | 8.08% (18/227) | 6.88% (12/166) |
Note. Unweighted numerator and denominator in parentheses. The pooled tertiary education gap across ages 18–55 is +13.34 pp, 95% CI [6.36, 20.33], p < .001 — the largest and most precisely estimated contrast in the study.
H1. Financial vulnerability by gender and age group
H1 predicted that the gender gap would differ between the two cohorts. Tested directly, it does not. The Female × Age 36–55 interaction gives OR = 0.53, 95% CI [0.16, 1.79], p = .307 without controls and p = .511 with them; under penalized estimation in the reduced specification, OR = 0.65, 95% CI [0.20, 2.16], p = .481. The difference between the two weighted gaps is 5.79 pp, 95% CI [−3.35, 14.93]. H1 is not supported.
The pooled gender gap in vulnerability across ages 18–55 is +4.16 pp, 95% CI [−0.44, 8.75], p = .076, and does not reach significance either. The submitted version reported that women aged 18–35 were more than twice as likely as men of that age to be vulnerable; that estimate did not survive correct variance estimation and is withdrawn. Two cautions apply to this null: the interaction interval is consistent with a substantial difference in either direction, and with 63 events the test was underpowered from the outset.
H2. Formal savings by gender
| Specification | OR or estimate | 95% CI | p |
| Weighted proportions, pooled 18–55 | −7.95 pp | [−15.29, −0.62] | .034 |
| Adjusted weighted ML, full | 0.618 | [0.425, 0.899] | .012 |
| Adjusted weighted Firth, full | 0.623 | [0.430, 0.904] | .013 |
| Adjusted weighted Firth, reduced | 0.600 | [0.415, 0.867] | .0065 |
| Weights trimmed at 5th / 95th percentile | 0.605 | — | .0070 |
| Clustering, ρ = .06 (m̄ = 10) | 0.600 | — | .028 |
| Manski bound: all 37 excluded coded as savers | 0.672 | [0.473, 0.954] | .026 |
| Manski bound: all 37 excluded coded as non-savers | 0.606 | [0.422, 0.871] | .0067 |
Note. The pooled estimand is primary. Reporting the 36–55 result as evidence of an age pattern would repeat the inference error identified in H1, since the between-cohort contrast is not significant (p = .424). The estimate is stable between 0.60 and 0.67 across every specification, and the extreme bounds are decisive: coding all 37 excluded respondents in the direction least favourable to the finding still leaves p = .026.
Women save at a financial institution less often than men, and this is the study’s single confirmatory finding. It survives penalized estimation, parameter reduction, weight trimming, plausible unmeasured clustering, and both extreme assumptions about excluded cases; Supplementary Table R5 reports each specification in full.
H3. Digital account ownership and vulnerability among women
The comparison rests on small cells: among women aged 36–55 without a digitally enabled account there are 6 vulnerability events in 26 cases, and among women aged 18–35 without one there are 3 in 20. Four estimators were fitted, and the pattern they produce is instructive.
Under design-based estimation the interaction is significant: weighted maximum likelihood gives OR = 0.092, 95% CI [0.015, 0.548], p = .009, and weighted Firth penalized estimation, which corrects the small-sample bias that inflates maximum-likelihood coefficients in sparse data, gives OR = 0.109, 95% CI [0.021, 0.574], p = .009. Penalization therefore moves the estimate very little. Discarding the survey weights moves it a great deal: unweighted Firth gives OR = 0.264, p = .113, and unweighted maximum likelihood OR = 0.241, p = .100. The divergence between specifications is driven by the weights rather than by the penalty, and unweighted estimators do not produce population quantities.
The interaction survives penalization, Holm correction within the pre-specified family (p = .020), and clustering up to ρ = .06 (p = .035). It does not reach conventional significance on the composite outcome, which combines the source and difficulty items, uses the full sample, and carries 174 events among women rather than 6 in the decisive cell: weighted Firth gives OR = 0.276, 95% CI [0.069, 1.099], p = .068. That specification addresses the design and the sparsity at once, and it falls just short.
H3 is therefore reported as supported on the primary outcome and not supported on the better-powered composite. The manuscript does not resolve the disagreement, because the data do not: the primary-outcome result is design-correct but rests on 6 events, while the composite is better powered but measures a broader construct. A leave-one-out analysis across all 411 observations found no single deletion that moves the unpenalized weighted p above .05 (range .004 to .022), so the result is not driven by a small number of high-weight respondents. Supplementary Table R7 reports all four estimators alongside the additional checks.
| Term | OR | 95% CI | p |
| Income Q3 (middle) vs Q1–2 | 0.814 | [0.397, 1.669] | .574 |
| Income Q4–5 (high) vs Q1–2 | 0.214 | [0.099, 0.462] | < .001 |
| Female | 2.056 | [0.834, 5.071] | .118 |
| Age 36–55 | 0.944 | [0.369, 2.420] | .905 |
| Female × Age 36–55 (H1) | 0.649 | [0.196, 2.155] | .481 |
| Tertiary education | 0.606 | [0.342, 1.075] | .087 |
| Employed | 0.643 | [0.331, 1.249] | .192 |
Note. Firth penalized estimation with linearized (sandwich) standard errors. The unpenalized full-specification odds ratio for the highest income quintile against the lowest is 0.084; that figure is inflated by sparse-data bias, and penalization in the same specification moves it to 0.102. The gradient is significant under every estimator tested, but the unpenalized estimate overstates its magnitude.
Income and education
Household income is the dominant gradient in financial vulnerability. Estimated as a total effect, tertiary education is associated with lower vulnerability (OR = 0.532, p = .034 unpenalized; OR = 0.545, 95% CI [0.308, 0.964], p = .037 penalized). Conditioning on income attenuates this to OR = 0.605, 95% CI [0.340, 1.077], p = .088, with about 20% of the coefficient transmitted through income. Because income lies on the causal path from education to financial outcomes, this pattern indicates mediation rather than irrelevance, and the manuscript does not claim that education fails to protect against financial vulnerability. Supplementary Table R4 gives the full decomposition.
Exploratory analyses and sensitivity
The urban–rural stratification was not pre-specified. The Female × Urban interaction gives OR = 1.16, 95% CI [0.32, 4.21], p = .824; given the sample size this null is uninformative rather than evidence of absence.
| Test | ρ = 0 | ρ = .03 | ρ = .06 | Holm |
|---|---|---|---|---|
| H2 savings gap, pooled adjusted (penalized) | .0065 | .0158 | .0284 | .0196 |
| H3 digital × age (weighted Firth, primary outcome) | .0090 | .0204 | .0353 | .0196 |
| H3 digital × age (composite outcome) | .068 | .105 | .141 | — |
| H1 gender × age interaction | .307 | .365 | .411 | .307 |
| Vulnerability gap, pooled (secondary) | .076 | .115 | .153 | — |
Note. The design effect from clustering is 1 + ρ(m̄ − 1), assuming an average cluster size of ten. The confirmatory family is the three pre-specified hypotheses, each evaluated with the estimator appropriate to its data structure; Holm–Bonferroni is applied across those three only, since correcting across every comparison reported in a paper would be over-correction. H2 and H3 both clear α = .05 across the full clustering band and under correction when H3 is estimated on the primary outcome; H3 does not clear it on the composite outcome, shown for comparison. Kazakhstan is surveyed face to face using multistage area probability sampling, so some clustering is certain and the reported standard errors are a lower bound.
Discussion
What these data establish
Two findings survive scrutiny. Women aged 18–55 hold tertiary qualifications about 13 pp more often than men, and they save at a financial institution less often, with an adjusted odds ratio near 0.60 that holds under every challenge tested. Household income is the dominant gradient in financial vulnerability, though its magnitude is smaller than the unpenalized estimate suggests. Three things are not established: the gender gap in emergency-fund capacity does not reach significance; the gender × age interaction is not supported, and the digital-account × age interaction holds only on the primary outcome; and the income-adjusted education association is not significant, which given the interval and event count indicates insufficient precision rather than absence.
Educational advantage without financial advantage
The central pattern is a mismatch, and at least three explanations are consistent with the data. The first is occupational: attainment may translate into different sectors and contract types for women, so equivalent qualifications yield unequal earnings stability. The Findex file records only household income quintile and a binary employment indicator, so this cannot be tested here.
The second concerns resources within households. A randomised trial that assigned ATM cards to newly opened Kenyan bank accounts found the resulting increase in account use concentrated in joint and male-owned accounts, with household bargaining power mediating the effect;28 and depositing wages into women’s own accounts has been found to change labour supply and gender-role attitudes three years later.29 Both suggest formal savings may understate what women accumulate, if resources held in visible institutional accounts are more easily claimed by others. Findex records informal saving separately, but the present analysis did not pre-specify it, and adding it now would be a post-hoc choice.
The third is measurement rather than substance. Both outcomes are self-reported. The gender gap in financial literacy has been found to persist in non-numerical contexts and is not attributable to differences in displayed confidence, but is mediated by financial anxiety.30 If an analogous asymmetry affects self-assessed capacity to raise emergency funds, part of any measured gap would reflect a reporting difference rather than a resource difference. The direction of such bias is itself contested; this study cannot determine which applies to the Findex items.
Income stratification and the comparison with Kenya
That income outweighs education replicates a well-established pattern rather than discovering one, as documented in the cross-country evidence above.1,2 Two readings compete: income may be the operative constraint, or it may proxy for unmeasured household characteristics such as wealth stocks and employment stability. Separating them would require data the Findex individual file does not contain.
The comparison most often drawn is with Kenya. A tempting inference is that digital financial services must operate through different mechanisms in Kazakhstan, where they expanded within an established banking system, given evidence that gains in Kenya were concentrated among female-headed households.4 A weaker claim is sufficient: the same mechanism can produce different observed associations when the counterfactual differs. In much of the Kenyan evidence the alternative to mobile money was no formal account at all; here, where 86% hold a digitally enabled account, the alternative is usually a different formal account. Two further lines complicate the picture. Market maturity rather than banking-system origin may be the operative difference,7 and a randomised agent rollout in poor rural northern Uganda found no increase in mobile money use, savings or remittances at all.31 The Kenyan results appear less like a general law than one outcome among several that depend on baseline conditions.
Interpreting the unsupported hypotheses
H1 failed, and two explanations compete: either the predicted age pattern does not exist, or it exists and this sample cannot detect it. The evidence does not separate these, and with 63 events the study was not equipped to answer the question it posed. H3 is a different case: it is significant on the primary outcome under design-based estimation and falls just short on the better-powered composite, so the direction is consistent across specifications while the significance is not. A larger sample is needed to settle it.
Implications
This study establishes a large educational advantage among women that does not appear in financial outcomes, and a moderate gender gap in formal savings that survives adjustment and sensitivity analysis. It does not establish a gender gap in emergency-fund capacity, any age patterning of either gap, or any causal effect of digital account ownership. Recommendations follow only from the first two.
The most direct implication is that financial inclusion policy measured by account ownership has reached its ceiling as an indicator in this setting. When 86% of adults hold a digitally enabled account and income still predicts resilience by a factor of roughly five, further gains in access are unlikely to change outcomes; frameworks tracking usage and buffer adequacy alongside ownership would capture more of what matters. The savings gap suggests a narrower target: because it persists after adjustment for income, education, employment and age, it is not explained by women in this sample being poorer or less educated. A further implication is methodological. The difference between weighted and unweighted estimation changed which results in this study survive, in both directions; analyses of Findex microdata that report unweighted proportions are not reporting population quantities.
Limitations
The sample is cross-sectional, so no result supports a causal claim, and it is small for the questions asked: 718 adults yielding 63 vulnerability events against eleven parameters is 5.73 events per variable. Vulnerability models are therefore reported in a reduced, penalized specification, and the unpenalized full-model estimates — including the income odds ratio — are inflated by sparse-data bias. The public release omits cluster identifiers, so every standard error here is a lower bound, and only the adjusted savings gap and, on the primary outcome, the digital-account × age interaction clear conventional significance across the full sensitivity band. Seventy respondents excluded for don’t know or refusal are unlikely to be missing at random, since uncertainty about raising emergency funds plausibly correlates with precarity; exclusion probably understates vulnerability. Extreme bounds are reported for the savings finding, which survives both, while equivalent bounds for the vulnerability estimates cross conventional significance. Under Holm correction across the three pre-specified hypotheses, the adjusted savings gap and the primary-outcome digital-account × age interaction remain below α = .05; the gender × age interaction does not.
On interpretation: financial vulnerability is measured by a single item, and resilience is multidimensional — the item captures neither buffer duration, nor the cost of raising funds, nor wealth, financial literacy, institutional trust or household composition. Institutional trust is among the more consequential omissions, since the cross-country evidence shows trust and inclusion moving together at the individual level while being inversely related across countries. The age boundary at 35 is defensible but not uniquely correct, and the upper bound at 55 excludes adults near pension age. The digital-account analysis was restricted to women because the hypothesis concerned women’s life stages, so the study cannot say whether the pattern examined is specific to women or a general age effect. Income enters as a household-level quintile and lies on the causal path from education, so the income-adjusted education coefficient is a direct effect and not a test of whether education matters. Finally, the literature search ran through English-language indexes, which cover Russian- and Kazakh-language journals unevenly.
Conclusion
Kazakhstan has closed the access gap in financial services and, for the outcomes examined here, has not closed the resilience gap. Women aged 18 to 55 hold tertiary qualifications about 13 pp more often than men, yet they are no less likely to report being unable to raise emergency funds and they save at a financial institution less often, with an adjusted odds ratio near 0.60 that persists after controlling for income, education, employment and age. What predicts financial vulnerability in this population is household income, by a wide margin.
Of the three hypotheses stated in the submitted version, one was not supported and one was supported only conditionally. The gender gap in vulnerability does not differ detectably between the two age cohorts; this null is not evidence of absence, since with 63 vulnerability events the study was underpowered for interaction inference and the confidence interval remains consistent with a substantial difference. The association between digital account ownership and vulnerability among women does differ by age on the primary outcome, but the result does not carry over to a better-powered composite measure and rests on a stratum of 26 women. Reporting these accurately rather than as originally claimed is the main way this revision differs from the version submitted, and the reason is that the original conclusions rested on comparing a significant subgroup result with a non-significant one — an inference a direct interaction test does not sustain.
Two directions follow. Establishing why women’s educational advantage does not appear in financial outcomes requires data pairing individual earnings with information on allocation within households; no such dataset currently exists for Kazakhstan, and building one would be more valuable than further analysis of existing cross-sections. Separately, the age-moderation questions posed here remain open rather than answered, and testing them would require either a substantially larger sample or pooling across the Central Asian countries that share Kazakhstan’s combination of high access and post-Soviet institutional history.
The wider point concerns measurement. An account-ownership rate of 86% describes a country that has solved a problem financial inclusion policy was designed to solve. It says nothing about whether the people holding those accounts could withstand an unexpected expense next month, and in this sample a large fraction could not. Access was the right thing to measure when it was scarce; where it is abundant, continuing to measure it mistakes an instrument for an outcome.
Supplementary Information
File 1: Robustness Supplement (Tables R1–R8 and Summary)
File 2: Full Replication Code
References
- A. Zins, L. Weill. The determinants of financial inclusion in Africa. Review of Development Finance. Vol. 6, No. 1, pg. 46–57, 2016, https://doi.org/10.1016/j.rdf.2016.05.001. [↩] [↩]
- F. Allen, A. Demirgüç-Kunt, L. Klapper, M. S. Martinez Peria. The foundations of financial inclusion: Understanding ownership and use of formal accounts. Journal of Financial Intermediation. Vol. 27, pg. 1–30, 2016, https://doi.org/10.1016/j.jfi.2015.12.003. [↩] [↩]
- A. Grohmann, T. Klühs, L. Menkhoff. Does financial literacy improve financial inclusion? Cross country evidence. World Development. Vol. 111, pg. 84–96, 2018, https://doi.org/10.1016/j.worlddev.2018.06.020. [↩]
- T. Suri, W. Jack. The long-run poverty and gender impacts of mobile money. Science. Vol. 354, No. 6317, pg. 1288–1292, 2016, https://doi.org/10.1126/science.aah5309. [↩] [↩]
- E. Riley. Mobile money and risk sharing against village shocks. Journal of Development Economics. Vol. 135, pg. 43–58, 2018, https://doi.org/10.1016/j.jdeveco.2018.06.015. [↩]
- C. Sakyi-Nyarko, A. H. Ahmad, C. J. Green. The gender-differential effect of financial inclusion on household financial resilience. Journal of Development Studies. Vol. 58, No. 4, pg. 692–712, 2022, https://doi.org/10.1080/00220388.2021.2013467. [↩]
- T. W. Reynolds, P. E. Biscaye, C. L. Anderson, C. O’Brien-Carelli, J. Keel. Exploring the gender gap in mobile money awareness and use: Evidence from eight low and middle income countries. Information Technology for Development. Vol. 29, No. 2–3, pg. 228–255, 2023, https://doi.org/10.1080/02681102.2022.2073579. [↩] [↩]
- L. Grzybowski, V. Lindlacher, O. Mothobi. Mobile money and financial inclusion in Sub-Saharan Africa. Information Economics and Policy. Vol. 65, pg. 101064, 2023, https://doi.org/10.1016/j.infoecopol.2023.101064. [↩]
- A. C. Preston, R. E. Wright. Understanding the gender gap in financial literacy: Evidence from Australia. Economic Record. Vol. 95, No. S1, pg. 1–29, 2019, https://doi.org/10.1111/1475-4932.12472. [↩]
- J. Espinoza-Delgado, J. Silber. Gender gaps in financial literacy: Evidence from Argentina, Chile, and Paraguay. Feminist Economics. Vol. 30, No. 1, pg. 134–171, 2024, https://doi.org/10.1080/13545701.2023.2278798. [↩]
- A. Cupák, P. Fessler, A. Schneebaum, M. Silgoner. Decomposing gender gaps in financial literacy: New international evidence. Economics Letters. Vol. 168, pg. 102–106, 2018, https://doi.org/10.1016/j.econlet.2018.04.004. [↩]
- A. Preston, L. Qiu, R. E. Wright. Understanding the gender gap in financial literacy: The role of culture. Journal of Consumer Affairs. Vol. 58, No. 1, pg. 146–176, 2024, https://doi.org/10.1111/joca.12517. [↩]
- J. Almenberg, A. Dreber. Gender, stock market participation and financial literacy. Economics Letters. Vol. 137, pg. 140–142, 2015, https://doi.org/10.1016/j.econlet.2015.10.009. [↩]
- L. Klapper, A. Lusardi. Financial literacy and financial resilience: Evidence from around the world. Financial Management. Vol. 49, No. 3, pg. 589–614, 2020, https://doi.org/10.1111/fima.12283. [↩]
- T. Beck, M. Brown. Foreign bank ownership and household credit. Journal of Financial Intermediation. Vol. 24, No. 4, pg. 466–486, 2015, https://doi.org/10.1016/j.jfi.2013.10.002. [↩]
- M. Brown, B. Guin, K. Kirschenmann. Microfinance banks and financial inclusion. Review of Finance. Vol. 20, No. 3, pg. 907–946, 2016, https://doi.org/10.1093/rof/rfv026. [↩]
- M. Bekturganova, M. Kurmasheva. Structural barriers and opportunities for financial inclusion of women in Kazakhstan. Eurasian Journal of Economic and Business Studies. Vol. 69, No. 2, pg. 19–33, 2025, https://doi.org/10.47703/ejebs.v69i2.492. [↩]
- S. Gaisina, L. Kaidarova. Financial literacy of rural population as a determinant of saving behavior in Kazakhstan. Rural Sustainability Research. Vol. 38, No. 333, pg. 32–42, 2017, https://doi.org/10.1515/plua-2017-0010. [↩]
- J. Kakhkharov. Migrant remittances as a source of financing for entrepreneurship. International Migration. Vol. 57, No. 5, pg. 37–55, 2019, https://doi.org/10.1111/imig.12531. [↩]
- S. Prina. Banking the poor via savings accounts: Evidence from a field experiment. Journal of Development Economics. Vol. 115, pg. 16–31, 2015, https://doi.org/10.1016/j.jdeveco.2015.01.004. [↩]
- Z. Fungáčová, I. Hasan, L. Weill. Trust in banks. Journal of Economic Behavior & Organization. Vol. 157, pg. 452–476, 2019, https://doi.org/10.1016/j.jebo.2017.08.014. [↩]
- A. Heyert, L. Weill. Trust in banks and financial inclusion: Micro-level evidence from 28 countries. Economic Systems. Vol. 49, No. 1, pg. 101248, 2025, https://doi.org/10.1016/j.ecosys.2024.101248. [↩]
- R. Matemane, M. Machokoto, T. T. Lemma, A. Majoni. Women, men, and money: A gendered analysis of financial resilience. Economics Letters. Vol. 253, pg. 112352, 2025, https://doi.org/10.1016/j.econlet.2025.112352. [↩]
- E. L. Wirba, F. A. Akem, E. N. Tingum. Implication of mobile money adoption for financial behaviour in Cameroon: A gendered analysis. Review of Behavioral Finance. Vol. 17, No. 6, pg. 1064–1081, 2025, https://doi.org/10.1108/rbf-02-2025-0081. [↩]
- J. C. Aker, R. Boumnijel, A. McClelland, N. Tierney. Payment mechanisms and antipoverty programs: Evidence from a mobile money cash transfer experiment in Niger. Economic Development and Cultural Change. Vol. 65, No. 1, pg. 1–37, 2016, https://doi.org/10.1086/687578. [↩]
- World Bank. The Global Findex Database 2025. World Bank, Washington DC, 2025. [↩]
- K. J. Rothman. No adjustments are needed for multiple comparisons. Epidemiology. Vol. 1, No. 1, pg. 43–46, 1990, https://doi.org/10.1097/00001648-199001000-00010. [↩]
- S. Schaner. The cost of convenience? Transaction costs, bargaining power, and savings account use in Kenya. Journal of Human Resources. Vol. 52, No. 4, pg. 919–945, 2017, https://doi.org/10.3368/jhr.52.4.0815-7350R1. [↩]
- E. Field, R. Pande, N. Rigol, S. Schaner, C. Troyer Moore. On her own account: How strengthening women’s financial control impacts labor supply and gender norms. American Economic Review. Vol. 111, No. 7, pg. 2342–2375, 2021, https://doi.org/10.1257/aer.20200705. [↩]
- G. Tinghög, A. Ahmed, K. Barrafrem, T. Lind, K. Skagerlund, D. Västfjäll. Gender differences in financial literacy: The role of stereotype threat. Journal of Economic Behavior & Organization. Vol. 192, pg. 405–416, 2021, https://doi.org/10.1016/j.jebo.2021.10.015. [↩]
- C. Wieser, M. Bruhn, J. Kinzinger, C. Ruckteschler, S. Heitmann. The impact of mobile money on poor rural households: Experimental evidence from Uganda. World Bank Policy Research Working Paper 8913, 2019, https://doi.org/10.1596/1813-9450-8913. [↩]